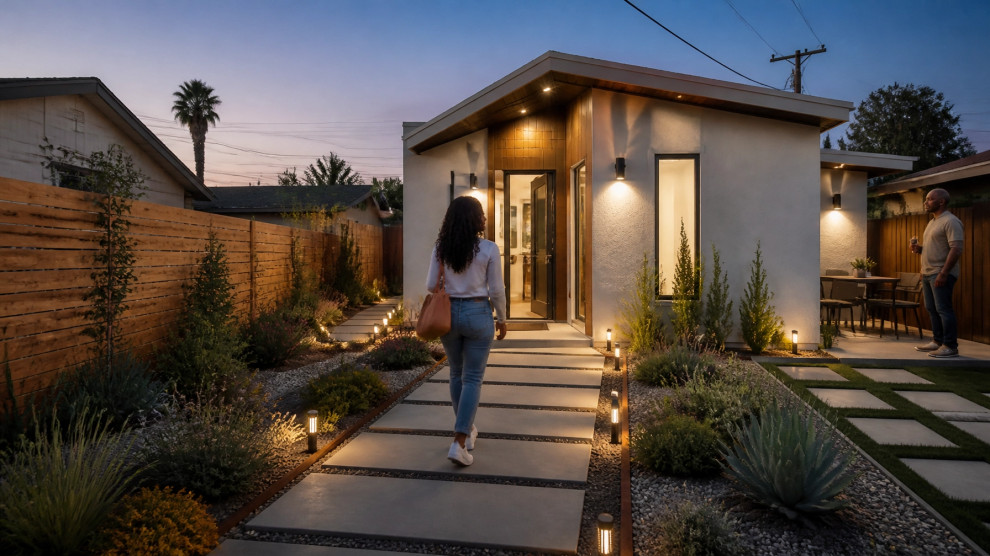
Does Your Homeowners Insurance Cover an ADU? 7 Questions to Ask Before You Break Ground
Are you considering an ADU in Los Angeles for a parent, adult child, guest, or long-term tenant? Before you finalize plans, you may be asking a practical question: Will your homeowners insurance cover the new space?
The answer is sometimes, but coverage depends on how the ADU is built, how it will be used, and how your insurer classifies it. A garage conversion, internal carve-out, attached addition, and detached backyard home may not receive the same treatment.
We recommend speaking with your insurance professional early: ideally before permitting or construction begins. These seven questions can help you prepare for that conversation and avoid relying on assumptions.
> Important: This article provides general information, not insurance, legal, tax, or financial advice. Your policy language and your insurer’s underwriting rules control your actual coverage.
First, understand what an ADU means for insurance
An accessory dwelling unit is a self-contained living space on the same property as your primary home. It typically includes its own entrance, kitchen, bathroom, and sleeping or living area.
In Los Angeles, your ADU might be:
- An attached addition or “bump-out”
- A garage conversion
- A second story above a garage or workshop
- An internal carve-out within your home
- A basement conversion
- A detached backyard cottage
According to Travelers’ ADU insurance guidance, attached or interior units may be treated as part of the primary dwelling, while detached units may fall under “other structures” coverage. However, those general categories do not guarantee that your ADU will be fully insured.
A detached ADU may have an “other structures” limit based on a percentage of your primary dwelling coverage. That amount might not be enough to rebuild a permitted, fully finished unit at current Los Angeles construction costs.
1. Will my ADU be classified as part of the main dwelling or as another structure?
Start with the basic classification.
Ask your insurer:
> “Will this ADU be covered as part of my primary dwelling, under other structures coverage, or through a separate policy or endorsement?”
The answer may depend on the design. For example, an internal ADU within your existing home may be treated differently from a detached backyard unit. A garage conversion may also be classified differently depending on whether the garage is attached or separate.
Bring your insurer a clear description of the project, including:
- Whether the unit is attached or detached
- Approximate square footage
- Number of bedrooms and bathrooms
- Whether it has a separate entrance
- Whether it has separate utilities or an address
- Whether it will be used by family or rented
This classification affects more than the structure itself. It may also influence personal property, liability, loss-of-use, and rental-income coverage.
2. Is the coverage limit enough to rebuild the ADU?
Choose coverage based on realistic replacement cost: not simply the amount you plan to spend today.
Ask:
> “What is my current limit, and would it be enough to rebuild this ADU after a covered loss using current Los Angeles labor and material costs?”
A small ADU can include a foundation, framing, roofing, insulation, windows, electrical, plumbing, HVAC, cabinets, flooring, appliances, and finishes. Rebuilding may also require debris removal, updated permits, engineering, and code-related improvements.
For a detached unit, ask specifically about the “other structures” limit. Many standard policies use a percentage of the primary dwelling limit, which may be insufficient for a permitted ADU.
Then ask whether your insurer offers:
- Increased limits for detached structures
- An ADU-specific endorsement
- Replacement-cost coverage
- Extended replacement-cost coverage
- Ordinance or law coverage
For instance, if your ADU includes custom cabinetry, durable flooring, or accessibility features for an aging parent, document those details. A simple square-footage estimate may not reflect the actual cost to restore the space.
3. What coverage applies while the ADU is under construction?
Do not assume your completed-home policy automatically covers every construction risk.
Ask:
> “Is the ADU covered during construction, or do I need builder’s risk or course-of-construction insurance?”
Construction can introduce risks that do not exist once the unit is complete. Materials may be stored on site, portions of the property may be open, and the unfinished structure may be more vulnerable to theft, vandalism, weather, or accidental damage.
Your insurer may ask about:
- The estimated construction period
- The total project cost
- Whether the unit is attached or detached
- Whether the property will remain occupied
- Who is responsible for construction-phase insurance
- Whether a lender requires specific coverage
Your contractor’s commercial general liability policy may address certain claims caused by negligence, but it is not necessarily a substitute for property coverage during construction. Ask your insurer and contractor to explain their responsibilities in writing.
At Coleman Build, we also encourage homeowners to verify that their contractor carries appropriate licensing and insurance before work begins. Our residential construction services can help you think through the project as a complete system: from planning and construction to the details that make the finished space feel welcoming.
4. How will the ADU’s intended use affect my policy?
Consider how the space will actually be occupied.
Ask:
> “Does coverage change if the ADU is used by family, rented to a long-term tenant, or offered as a short-term rental?”
An ADU used by an aging parent or adult child may be handled differently from one rented to someone outside the family. Long-term rental use can require landlord or dwelling-fire coverage, an endorsement, or another policy structure.
Short-term rentals can create additional questions. Some insurers offer home-sharing endorsements, while others may exclude or restrict certain claims connected to paying guests.
Be ready to explain:
- Who will live in the unit
- Whether rent will be collected
- Whether a lease will be used
- Whether the unit will be listed on Airbnb or another platform
- Whether you will provide furnishings
- Whether the ADU will ever be vacant
The Liberty Mutual ADU insurance guide similarly emphasizes matching coverage to the ADU’s use. Clear information helps your insurer recommend coverage that aligns with your plans.
5. Does my liability coverage extend to the ADU and its pathways?
Think beyond the walls.
Ask:
> “Does my personal liability coverage extend to injuries or property damage connected with the ADU, entrance, walkway, driveway, and shared outdoor areas?”
An ADU creates another living area: and potentially more people moving through your property. A guest, tenant, delivery person, or family member might use a side gate, pathway, stairs, porch, or shared yard.
Ask whether your current liability limits are appropriate and whether an umbrella policy might be worth considering, particularly if you plan to rent the unit. An umbrella policy generally provides additional liability protection above the limits of underlying policies, but it does not replace property insurance for the ADU.
Also ask whether your insurer has safety requirements involving:
- Exterior lighting
- Handrails and guardrails
- Address visibility
- Smoke and carbon monoxide alarms
- Locks and entry doors
- Pools, spas, or other shared amenities
Thoughtful design can support both daily comfort and risk management. For example, a well-lit path, lever-style door handles, and clear transitions can make an ADU more welcoming for an older family member while also improving accessibility.
6. What documents do you need from me and my contractor?
Prepare before you call.
Ask:
> “Which project documents will you need to add or rate the ADU correctly?”
Your insurer may request information such as:
- Architectural plans
- Building permits
- Final inspection or certificate of occupancy
- Construction contract
- Estimated or final construction cost
- Square footage
- Roof and exterior materials
- Electrical, plumbing, and HVAC details
- Photos of the completed unit
- Contractor license and insurance information
Keep invoices and finish schedules, too. Cabinet hardware, appliances, windows, flooring, and accessibility upgrades all contribute to the cost and character of the finished space.
You should also ask when to update your policy. Some insurers may want notice before construction starts, while others may finalize permanent coverage after the project is complete and the permit is closed. Get the timing in writing.
Our projects page shows the range of residential work that can shape a property: from kitchens and flooring to larger home improvements. That same level of documentation and attention can help make your ADU easier to describe accurately.
7. Are earthquake, wildfire, flood, and code-upgrade losses covered?
Review the risks that matter in Los Angeles.
Ask:
> “Are earthquake, flood, wildfire-related losses, and upgrades required by current building codes covered for this ADU?”
Standard homeowners insurance does not necessarily cover every type of catastrophe. Earthquake coverage, for example, may require a separate policy or endorsement. Flood coverage may also be separate, even when water enters after a severe storm.
Wildfire planning deserves careful attention in many Los Angeles communities. Ask how your insurer handles:
- Fire damage to the ADU
- Debris removal
- Landscaping near the structure
- Rebuilding after a total loss
- Increased rebuilding costs
- Ordinance or law requirements
- Defensible-space or mitigation documentation
A permitted ADU may need to be rebuilt to current codes after a major loss. Ordinance or law coverage may help with certain added expenses, but the terms vary by policy.
Do not wait until after a loss to discover that the ADU was never listed or that a coverage exclusion applies. Request updated declarations pages and endorsements once coverage is arranged.
A simple checklist for your insurance call
Before contacting your insurer, gather:
- Your ADU type: attached, detached, garage conversion, addition, or internal unit
- Approximate size and room count
- Estimated construction cost
- Intended use: family, long-term rental, or short-term rental
- Plans, permits, and contractor information
- Details about separate entrances, utilities, or addresses
- Questions about liability, replacement cost, rental income, and catastrophe coverage
Then request written confirmation of how the ADU will be insured.
Build with clarity from the beginning
So, does homeowners insurance cover an ADU? It may: but coverage is not automatic, and the right answer depends on your property, policy, project stage, and intended use.
When you ask these seven questions before breaking ground, you gain a clearer budget, a more coordinated construction plan, and greater confidence in the finished space. Whether you are creating a private home for family or a flexible rental opportunity, our team can help you move forward thoughtfully.
At Coleman Build, we believe every detail matters. If you are planning an ADU or remodeling your Los Angeles home, contact our team to begin a collaborative conversation about what your property: and your future: could make possible.